San Diego County is home to one of the largest military communities in the country, and we’ve helped many military families navigate their home purchase over the years. The Veterans Affairs (VA) home loan helps eligible veterans, active-duty service members, and surviving spouses buy, build, repair, retain, or adapt a home to live in. It’s one of the strongest home-buying benefits available, yet plenty of people who’ve earned it aren’t sure how it works. Let’s clear up the most common myths about the topic.
Common VA Loan Misconceptions, Explained
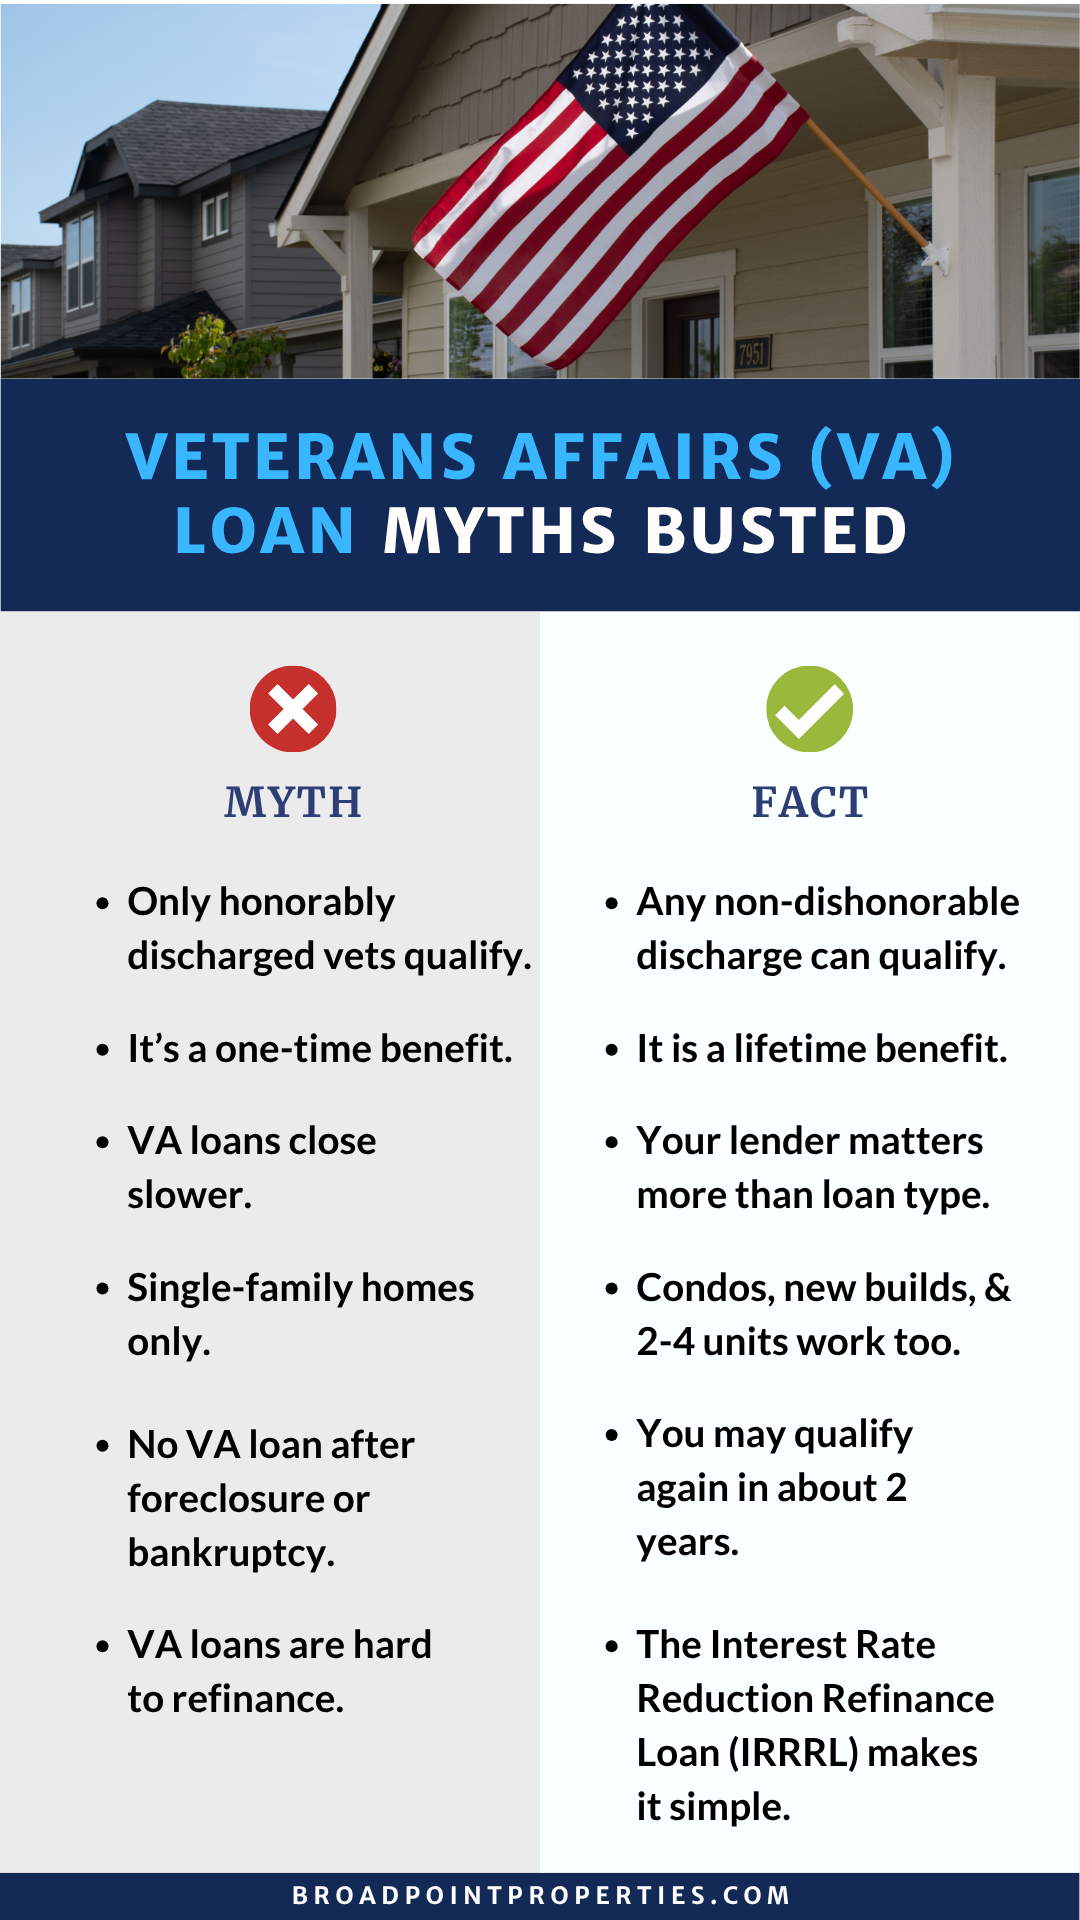
Myth #1: VA loans are only for honorably discharged veterans.
Fact: The requirement is a discharge under conditions other than dishonorable. Veterans, active-duty service members, National Guard and Reserve members who meet service requirements, and eligible surviving spouses can all qualify. A Certificate of Eligibility (COE) confirms your status.
Myth #2: It’s a one-time benefit.
Fact: It’s reusable. Once you pay off a VA loan, you can restore your entitlement and use the benefit again. If you still have entitlement left, you may even hold more than one VA loan at a time, provided you qualify with your lender. And a past foreclosure doesn’t permanently close the door.
Myth #3: VA loans take longer to close than FHA or conventional loans.
Fact: Closing time depends far more on your lender and how prepared you are than on the loan type. Industry data has shown VA loans closing a few days slower than conventional loans in some periods and faster in others. Getting your COE early and working with a lender experienced in VA loans keeps things moving.
Myth #4: VA loans only work for traditional single-family homes.
Fact: VA loans can finance single-family homes, condos in VA-approved projects, new construction, manufactured homes on a permanent foundation, and 2–4 unit properties as long as you live in one unit. They can’t be used for vacant land (unless you’re building your home on it), co-ops, or vacation, investment, or business properties.
Myth #5: You can’t get a VA loan after a foreclosure or bankruptcy.
Fact: VA loans are among the most forgiving after a financial setback. A common guideline is two years after a foreclosure or Chapter 7 discharge, and Chapter 13 filers may qualify sooner with on-time payments and court approval. Lenders can set their own stricter rules, so it’s worth asking.
Myth #6: VA loans can’t be refinanced easily.
Fact: Current VA borrowers can use the Interest Rate Reduction Refinance Loan (IRRRL) to lower their rate or move to a more stable payment, usually with simpler paperwork than a standard refinance.
Learn more about the perks of getting a VA loan vs a regular mortgage here.
You’ve served our country. Now let us serve you. If you’re ready to put your VA benefit to work, call the agents at Broadpoint Properties.
Disclaimer: Eligibility and terms are determined by the VA and your lender